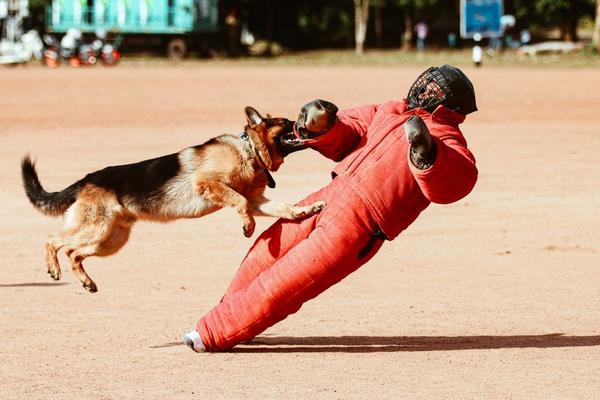
A friendly dog, an open front door, and a startled delivery driver can turn an ordinary afternoon into an expensive liability claim. Does homeowners insurance cover dog bites? Usually, yes. A standard U.S. policy’s personal liability coverage may help pay medical costs, settlements, and legal expenses when your dog injures someone else. But the answer depends on exclusions, your dog’s history, and the incident itself.
Dog bite liability under homeowners insurance is not guaranteed just because you have an active policy. Knowing the boundaries before an accident can prevent a costly surprise.
What Part of Homeowners Insurance Covers Dog Bites?
Dog-related injuries generally fall under personal liability coverage, not the protection that repairs your house. If you’re legally responsible for hurting someone, liability insurance may pay covered damages up to the applicable limit. The Insurance Information Institute says homeowners and renters policies typically cover dog bite liability, subject to policy terms.
Personal liability versus medical payments
Personal liability can address significant medical bills, lost income, settlements, and legal defense arising from a covered incident. Whether attorney fees reduce the liability limit depends on your contract.
Medical payments to others is different. This smaller coverage may help pay a visitor’s immediate medical expenses without establishing legal responsibility. Its lower limit makes it no substitute for liability protection after a serious injury.
Does Coverage Apply Away From Your Property?
Often, yes. Homeowners liability protection commonly follows insured household members beyond the property. A covered bite during a neighborhood walk or at a friend’s home may qualify. Location alone does not decide a dog bite insurance claim.
Who was injured also matters. Guests, neighbors, delivery workers, and strangers may qualify as third parties. Injuries to you or other insured household members generally are not covered under the same liability provision. Business-related incidents may trigger separate exclusions.
When Can a Dog Bite Claim Be Denied?
You can have a valid homeowners policy but no coverage for a particular dog. Read the policy and all endorsements, which can change standard coverage.
Breed restrictions and animal exclusions
Some insurers restrict dogs based on breed or perceived risk; others assess individual behavior. The National Association of Insurance Commissioners notes that breed lists remain controversial, and some states restrict decisions based solely on breed.
Breed restrictions in homeowners insurance vary. One insurer might decline an application, another might exclude one dog, and a third might cover it normally. Do not assume your homeowners policy automatically includes pet liability coverage without asking.
Prior bites, nondisclosure, and intentional conduct
A previous bite or documented aggressive behavior can affect underwriting. Where permitted, insurers may raise premiums, exclude the dog, or decline renewal. Inaccurate answers about a dog’s history can also create coverage problems under applicable law.
Deliberately caused injuries are generally excluded. But an ordinary accident does not automatically become intentional because an owner failed to predict the dog’s reaction. The specific facts and contract matter.
How State Dog Bite Laws Affect Liability
Insurance coverage and legal responsibility are separate questions. State law helps determine when an owner is liable; the policy determines whether the insurer must defend or pay a covered claim.
Some states impose strict liability for qualifying bites even without a known history of aggression, subject to exceptions. Other cases depend on negligence, such as violating a leash rule, or evidence that the owner knew the dog was dangerous. The so-called one-bite rule is not blanket immunity for a first attack.
Provocation, trespassing, local ordinances, and the type of injury can change the result. State-specific legal advice may be necessary after a serious incident.
How Much Will Insurance Pay?
Many policies offer personal liability limits of $100,000 or $300,000, although yours may differ. Some impose lower animal-liability sublimits. If covered damages exceed the applicable limit, the remaining amount may become your personal responsibility.
Consider a hypothetical example: a dog bites a visitor, and medical expenses, lost wages, and settlement costs total $140,000. If the available covered liability limit is $100,000, the owner could face a $40,000 shortfall. Actual payment depends on fault, exclusions, and defense-cost provisions.
Higher limits may be available through umbrella insurance. However, additional limits do not automatically restore coverage excluded under the underlying policy. Understanding how umbrella insurance works can help you ask better questions before buying it.
What to Do After Your Dog Bites Someone
Secure the dog, check the injured person’s condition, and encourage appropriate medical care. Exchange contact information and provide vaccination details. Follow local reporting requirements involving animal control or public health officials.
Notify your insurer promptly, even if the injury appears minor. Document the incident with a factual account, photographs, witness details, and official reports. Save correspondence. Avoid promising payment on the insurer’s behalf, guessing about fault, or ignoring legal notices.
For example, if your dog escapes through an open gate and knocks down a courier, report the event even if there is no puncture wound. Dog liability claims also arise from falls and other injuries. Ask the adjuster which documents the insurer needs.
Check Your Coverage Before There Is a Claim
Request written confirmation that your specific dog is covered. Ask whether breed or bite-history restrictions apply, whether incidents away from home qualify, and whether there is an animal-liability sublimit. Confirm how legal defense costs are handled.
If your policy excludes the dog, explore standalone canine liability insurance or a different homeowners insurer. Compare exclusions alongside premiums. Knowing what homeowners insurance exclusions mean can make policy comparisons more useful.
Frequently Asked Questions
Does homeowners insurance cover a first dog bite?
Often, provided the claim meets policy conditions and no exclusion applies. A first bite does not guarantee either coverage or freedom from legal liability.
Can insurers reject coverage because of breed?
Depending on state law, an insurer may restrict certain breeds or exclude animal liability. Some states limit breed-only underwriting decisions, so check local rules and your written policy.
Will a dog bite claim raise my premiums?
It can. Insurers may increase rates, change terms, or decline renewal where legally permitted. Outcomes depend on the incident, claims history, insurer, and state.
Does renters insurance cover dog bites?
Many renters policies include personal liability coverage for qualifying dog-related injuries. Exclusions, limits, and prior bite history still matter.
The Bottom Line
Homeowners insurance often covers dog bites through personal liability protection, but coverage is never automatic. Review animal exclusions, check your limits, and understand local law. Asking your insurer whether your specific dog is covered both at home and elsewhere is one of the simplest ways to avoid a damaging surprise.